Monday, October 19, 2026 · Trucking & Freight
China Container Freight Rates Diverge by Route as August CCFI Slips
Noted by Michael Davis · 732 reads
China’s CCFI fell 1.9% in August while the SCFI rose 6.8%, with rate trends varying across major trade lanes.
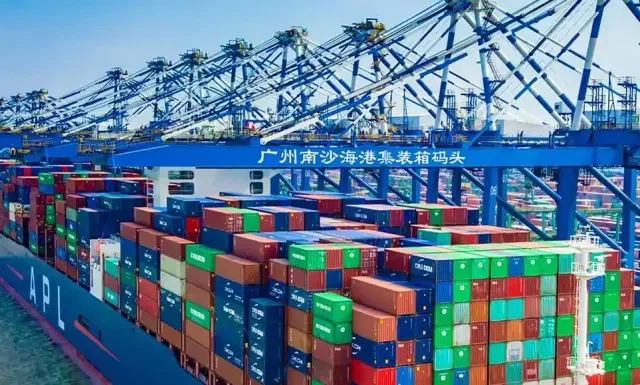
China’s container export market held broadly steady in August 2026, but that headline masks sharply different conditions by route. The China Containerized Freight Index (CCFI) edged down, while spot prices tracked by the Shanghai Containerized Freight Index (SCFI) climbed. For shippers, the practical issue is where freight is moving and how much volume is exposed to spot pricing.
The Shanghai Shipping Exchange Research Institute (preparatory) reported an August average CCFI of 1,835.55 points, down 1.9% from July. The SCFI averaged 3,387.64 points, a 6.8% month-on-month increase. These indices cover different parts of the rate market: the SCFI follows spot rates and responds quickly to short-term changes, while the CCFI includes a broader mix of rates, including contract pricing, and tends to adjust more slowly.
That split gives shippers a useful read on their exposure. Companies relying heavily on spot bookings saw higher prices reflected in the SCFI, while contracted cargo was covered by a broader rate measure that moved lower. Neither index alone describes every lane, but together they show why an overall market reading can diverge from an individual shipper’s experience.
Export demand supports the market
China’s exports rose 23.9% year on year in U.S. dollar terms in July, based on the latest data from the General Administration of Customs. That growth provides a strong demand backdrop for container shipping, even as August indicators pointed in different directions across rates and routes.
Port container throughput dipped slightly in August compared with July. The decline was limited and did not materially alter the market’s overall stability. The combination of strong July export growth and a modest monthly pullback in port handling suggests that demand and operating volumes did not move in lockstep over the period. Shippers planning capacity should therefore keep both export demand and lane-specific rate signals in view.
The vessel charter market also continued to rise. Carriers lease ships from shipowners, and higher charter rates add to the cost of putting extra capacity into service. Those costs can affect the rates and service options carriers offer cargo owners. For shippers and forwarders, a firmer charter market is a reason to track carrier capacity plans and secure space early where dependable coverage matters.
European lanes adjust as spot costs climb elsewhere
Rates on routes to Europe and the Mediterranean shifted in August as carriers and shippers responded to changing lane conditions. The available data describes an adjustment, rather than a break in the market’s broader stability. Shippers serving European customers will need current lane-level pricing to judge how the change affects their own bookings.
Reviewing the balance between spot and contract volumes can help cargo owners manage rate exposure while protecting delivery commitments. Regular checks on rate structures also help procurement teams avoid relying on a composite index that may not reflect the prices available for a particular origin, destination or service.
North American routes moved in the other direction: spot freight rates rose during the month, in line with the SCFI’s 6.8% increase. Shippers with significant spot exposure on transpacific lanes faced higher costs. For importers, those increases can feed into landed-cost calculations, inventory timing and cash-flow plans.
Forwarders can help clients compare spot bookings with longer-term contract options as prices change. The right mix depends on a shipper’s route, volume and need for space, but August’s figures make the trade-off clear: spot costs rose even while the broader CCFI declined.
Middle East and Oceania strengthen; Japan eases
The freight index for the Red Sea and Persian Gulf route rose in August, pointing to firmer pricing on services linking China with the Middle East. Cargo owners moving goods on this lane should account for the higher-rate environment when quoting customers and setting delivery schedules. Keeping close contact with carriers and forwarders can help teams respond as cost and transit conditions change.
On the Australia-New Zealand trade, the market stabilized and rebounded during the month. That shift gives shippers a firmer basis for planning than earlier, softer conditions, while making continued rate monitoring important as procurement decisions are set.
Japan-bound rates edged down slightly, contrasting with gains on several other major routes. The softer pricing offers cargo owners serving Japanese customers a chance to manage costs on this short-haul trade. It also underlines why route-level information matters: a composite index can conceal differences between neighboring or otherwise distinct markets.
August’s figures point to a stable composite market with meaningful variation beneath the surface. Strong export growth supports demand, while higher charter costs and rising spot prices on selected lanes complicate budgeting. Shippers will get the clearest view by matching rate data to their own routes and booking mix, then adjusting space and cost plans accordingly.