Tuesday, October 27, 2026 · Trucking & Freight
Diesel Prices Hit Records as Refining Constraints Widen the Gap With Gasoline
Noted by Adam Wingfield · 840 reads
Diesel reached about $6.50 per gallon as refining losses and regional supply constraints outpaced crude’s influence, squeezing carriers and fuel surcharge recovery.
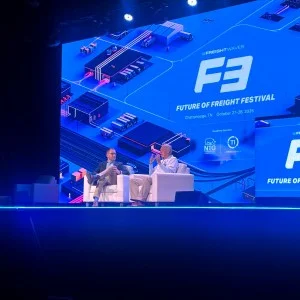
Diesel’s record price is creating a direct cost problem for carriers, while gasoline remains well below its previous peak. GasBuddy analyst Patrick De Haan told an F3 audience that the divergence reflects tighter refining capacity and uneven regional supply more than the crude oil price alone. For trucking operations, the gap matters twice: fuel costs vary sharply by location, and weekly surcharge benchmarks can lag fast changes at wholesale.
De Haan’s perspective draws on GasBuddy’s tracking of gasoline and diesel prices at roughly 150,000 stations in the United States and Canada. He described the period since March as the most volatile he has observed. Prices eased in June and July before rising again in August and September, without settling into a predictable pattern.
average gasoline and diesel prices stubbornly holding in familiar territory: $4.26/gal for gasoline, $6.35/gal for diesel. prices may slip a few cents but long term relief remains elusive.
— Patrick De Haan (@GasBuddyGuy) October 27, 2026
Diesel and gasoline take different paths
Diesel climbed above its 2022 record of $5.81 per gallon, reached about $6.50 a few weeks before the event, and then eased to roughly $6.35, De Haan said. Gasoline was about 70 cents below its own 2022 peak. During that earlier run-up, both fuels set records and generally moved together. This time, their prices have separated.
That split reflects the different markets for crude oil, gasoline, diesel and jet fuel. Crude is a starting material; refineries determine how much of each usable product reaches the market. When processing capacity is constrained, available crude alone doesn’t ensure that diesel supply will meet demand.
De Haan pointed to a loss of refining capacity as a key backdrop. Crude grades also matter: refineries are configured for particular blends, and heavier crude can yield more heavy products, including diesel. He said Iran produces roughly 55% heavy crude and noted ongoing attention to Venezuelan barrels that can be difficult to process. A refinery generally can’t switch freely between crude types, so pressure on heavy crude supplies or on plants designed to process them can weigh particularly on diesel output.
Capacity constraints and export flows
Diesel has typically cost more than gasoline for about two decades, a gap that widened after ultra-low-sulfur diesel specifications took hold around 2006. The capacity picture has also shifted: De Haan said China overtook the United States as the world’s largest refiner within the past year. He described China’s reduced refining output, intended to protect access to crude and strategic reserves, as a factor removing supply from an already tight global market.
Another pressure came from Russia’s pullback in diesel exports. De Haan estimated that Russia accounts for about 10% of global diesel production. Refinery damage associated with drone activity, which began the previous October and became more effective as the technology advanced, reduced Russian processing and contributed to domestic fuel rationing. With less product available for export, international buyers had fewer barrels to draw on.
Crude prices were already under pressure earlier in the year amid concerns involving the Strait of Hormuz and Iran. The resulting market faced two forces at once: a higher crude cost and less refining capacity. De Haan’s account suggests the crude move lifted the underlying price, while the loss of refined supply helped push diesel to records.
Regional prices reflect infrastructure
North American wholesale diesel pricing starts with the NYMEX ultra-low-sulfur diesel contract, which De Haan described as a delivered New York Harbor barge price before taxes. Local refining balances and transportation links then shape what buyers pay. Depending on the market, regional wholesale differences can reach 40 to 60 cents per gallon.
The Colonial Pipeline carries fuel from the Houston area north through the mid-Atlantic toward New York. De Haan compared it to an aorta serving markets along its route. The Gulf Coast has the country’s largest concentration of refining capacity and is usually among the least expensive regions. Markets in parts of the lower and mid-Atlantic can also benefit from direct pipeline access.
That export capacity can change the Gulf Coast’s position when European buyers seek diesel that was previously supplied by Russia. The West Coast tends to be more expensive, De Haan said, citing high taxes and reduced refining capacity in California. The Great Lakes region has also seen recent price increases linked to local refinery trouble; its plants depend on crude from western Canada.
Fast wholesale changes test carrier budgets
Wholesale prices, commonly called the rack, have historically reset once near the end of the day, around 5 or 6 p.m. De Haan said that during parts of March and April, prices moved within the day. The wholesale difference between fueling at 5:55 and 6:05 could reach 50, 60, 70 or even 80 cents per gallon. Such swings make fuel purchasing costs harder to predict from yesterday’s price.
Retail prices don’t immediately mirror every wholesale move. Stations may take one to three days to pass increases through, and prices can be slow to fall when wholesale costs ease. Underground tanks turn over faster than some buyers expect: De Haan put the average at two to four days, with faster turnover at high-volume truck stops. That means the price at the pump can reflect recent supply costs, not fuel purchased many days earlier.
For carriers, the timing mismatch also affects fuel surcharge recovery. Many programs use the U.S. Department of Energy’s weekly national average on-highway diesel price. A single weekly figure can lag a market where wholesale prices shift sharply during the day and regional differences reach dozens of cents per gallon. A carrier buying fuel on the West Coast, in the Great Lakes during refinery trouble, or on an export-driven Gulf Coast may pay more than the benchmark implies.
When the index trails a rapid increase, the surcharge may not cover the carrier’s full fuel bill. Recovery can also take time after prices retreat. The practical measure is the difference between actual fuel expense and surcharge income across the lanes a fleet runs; relying on the national weekly figure as a close match for every truck can leave that gap hidden in operating costs.
Track diesel on its own terms
De Haan argued that oil producers are price takers rather than price makers, pointing to January and February, when crude was between $50 and $60 per barrel and producers were not thriving. He also said convenience stores have recently had unusually high retail margins, while increasingly earning money from products other than fuel.
Forecasts entering 2026 had widely anticipated a crude glut, but De Haan said that expectation ended on March 1. He saw no quick return to a calm, well-supplied market. For carriers, his account points to a more useful planning approach: monitor diesel prices, regional supply and refining conditions alongside crude. Surcharge performance should be checked against the actual lanes and purchase timing, because the benchmark may not capture the cost a fleet faces at the pump.
This article is based on an F3 conversation with Patrick De Haan, head of petroleum analysis at GasBuddy. Price figures, dates and market characterizations reflect the speaker’s account at the event. Fuel surcharge mechanics reflect common industry practice tied to a weekly national diesel price index.
The post Diesel Is Breaking Records While Gasoline Stays Cheap, And The Reason Is Not What Most Truckers Think appeared first on FreightWaves.